

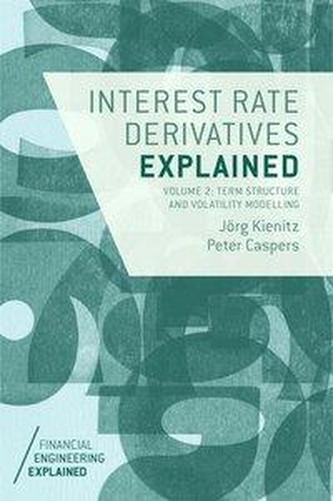
Interest Rate Derivatives Explained: Volume 2
1251 Kč
Sleva až 70% u třetiny knih
Such models are necessary to account for the volatility skew/smile and form the fundament for pricing and risk management of complex interest rate structures such as Constant Maturity Swap options. We consider three main classes namely short rate models, instantaneous forward rate models and market models.
| Autor: | Kienitz, Jorg; Caspers, Peter |
| Nakladatel: | Palgrave Macmillan |
| ISBN: | 9781137360182 |
| Rok vydání: | 2017 |
| Jazyk : | Angličtina |
| Vazba: | Hardback |
| Počet stran: | 248 |
Mohlo by se vám také líbit..
-
Principles of Economics
Marshall, Alfred
-
Financial Modeling
Hacker, Hans-Joachim
-

Health Economics
Bhattacharya, Jay; Tu, Peter; Hyde, Timothy
-
Multinational Corporations from Emer...
-
Labour Market Flexibility and Pension...
-
An Introduction to Behavioral Economics
Wilkinson, Nick
-
Microeconomics
Raa, Thijs Ten
-
Modern Money Theory
Wray, L. Randall
-
Strategy and Sustainability
Rosenberg, Mike
-
The Industrial Policy Revolution I
Lin, Justin Yifu
-

Capital Returns
-
The Future of Private Equity
Bishop, Mark
-
Experimetrics
Moffatt, Peter
-
The Economics of Welfare
Pigou, A. C.
-
Strategy and Policy for Trans-Europea...
Johnson Debra, Turner Colin,
-
The Transatlantic Eco-Romanticism of ...
Tovey, Paige